The Exit Clause Is the Contract: Pricing Withdrawal on a 2026 UK Charter
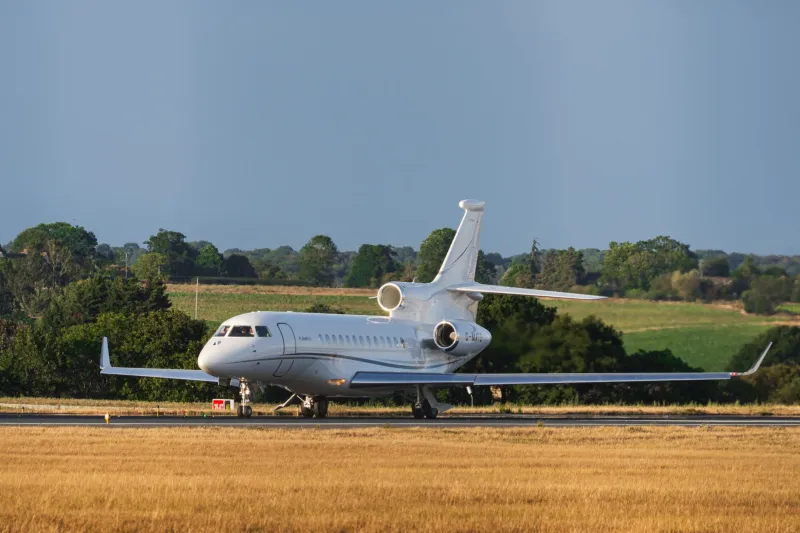
Photo: Zuluklobravo, CC BY 4.0, via Wikimedia Commons
For many UK charter buyers, the rate card receives the closest reading and the cancellation schedule is left to the closing pages. That ordering is understandable but expensive. A private charter is not a seat held in a queue; it is a set of commitments made on the buyer's behalf, often before the passenger has confirmed the final meeting time. The exit clause therefore deserves the same scrutiny as the aircraft type, the operator's AOC and the handling arrangements.
The central point is simple: cancellation exposure is rarely a single percentage applied to a single date. It is a ladder. Each rung reflects what the operator has already bought, reserved or declined in order to protect the charter. The buyer who understands how that ladder is built can negotiate from evidence rather than from the headline figure.
The ladder begins before the first invoice
A charter quotation may look like one price, but it sits on several layers: aircraft availability, crew duty, positioning, fuel, airport slots, handling, permits and, in winter, de-icing. Some of these costs are refundable or transferable; many are not. The first deposit is often described as a commitment fee, but its practical purpose is to begin converting a provisional booking into a scheduled operation.
That is why a cancellation schedule should be read alongside the operator's internal milestones. At what point is a tail number allocated? When is the crew formally rostered? When are slots requested and confirmed? When is fuel ordered? When does the handling agent require a final movement message? These moments matter more than the calendar date alone, because they determine whether the operator has merely lost a prospect or has already spent money and declined other work.
A buyer should also check the base to which any percentage applies. Is it the charter price only, or does it include ferry legs, crew overnight costs, handling, landing fees and VAT? A seemingly moderate percentage applied to a broad base can produce a larger bill than a higher percentage applied narrowly. The same discipline applies to taxes and airport charges: some may be recoverable if the flight does not operate, while others may already have been paid away.
What the operator has already bought
The most useful negotiation is not an argument about whether cancellation should cost something. It is a discussion about what has actually been committed. For a London departure, the operator may have secured a slot at Luton, Farnborough or Biggin Hill, confirmed handling, rostered a crew and arranged for an aircraft to remain in position rather than accept another charter. On a European business route, the positioning leg may already have been flown or planned around crew duty limits.
These are not abstract costs. Crew duty has a commercial value because the operator must hold the crew available and may be unable to replace them at short notice. Aircraft commitment has a value because the tail number could have been sold elsewhere. Positioning has a value because ferry time is real flying time. Handling and slots have a value because they are third-party services with their own cancellation terms.
A practical buyer therefore asks for the operator's commitment milestones in writing. The question is not simply what percentage applies at 72 hours, but what the operator will have done by 72 hours. If the answer is that the aircraft will already have positioned and the crew will already be on duty, the cancellation charge is easier to understand and easier to test.
Force majeure is not a magic word
Force majeure clauses are often treated as a general escape route. In practice, they should be narrow, documented and symmetrical. A passenger's change of commercial plans is not force majeure. A closed airport, a government restriction, a named storm or a medical emergency may be, depending on the wording and the evidence required. The clause should state who decides whether an event qualifies, what notice is required, what proof is needed and how refunds or credits are calculated.
Buyers should also distinguish between cancellation by the passenger and inability of the operator to perform. If the operator cannot supply the contracted aircraft or crew, the buyer's remedies should be clear. If the buyer cancels for a reason that is outside the operator's control but not within the clause, the ordinary cancellation ladder should apply. Ambiguity here is costly because it invites dispute at the very moment when decisions must be made quickly.
A further question concerns third-party charges. Even where a force majeure clause allows cancellation, airport charges, handling fees and taxes may have different recovery rules. The clause should identify which sums are refundable, which are creditable and which are lost. It should also set a timetable for repayment rather than leaving the buyer to chase an unspecified balance.
Rebooking credits and the operator's diary
A rebooking credit can be a sensible compromise, but it is not equivalent to a refund. Its value depends on expiry, transferability, price protection and the financial standing of the party granting it. A credit against a broker may be less secure than a credit against the operator, particularly if the broker is not the contracting carrier. A credit that expires within six months may be of little use to a buyer whose travel pattern is seasonal.
The operator's diary is the other side of the ledger. If a cancelled charter is resold, the operator may recover some or all of the lost revenue. A well-drafted clause can require the operator to apply reasonable mitigation and to pass on a defined benefit if the slot is relet. This is not a demand for a windfall; it is a way of aligning the final bill with the operator's actual loss.
Positioning costs deserve particular attention. If the aircraft has already flown to the departure airport, or if a crew has been positioned, those costs may sit outside the percentage schedule. The buyer should ask whether ferry legs, crew travel and overnight expenses are treated as committed costs and how they are evidenced. A cancellation at 24 hours may therefore be more expensive than the percentage alone suggests.
Questions to put to the operator before signing
A buyer does not need to negotiate every line to improve the outcome. A focused set of questions will usually reveal whether the cancellation schedule is commercial and transparent. Ask for the full schedule by date and time, the base to which each percentage applies, and a worked example using the actual charter price. Ask which third-party costs are non-refundable and what evidence will be provided if they are claimed.
Ask when the tail number is allocated and when the crew are rostered. Ask whether the aircraft will position before departure and how ferry time is treated on cancellation. Ask how force majeure is defined, who determines it and what notice is required. Ask whether rebooking credits are transferable, how long they last and whether they are protected if the operator or broker ceases trading. Finally, ask whether the operator will apply mitigation credit if the cancelled slot is resold.
A framework for comparing clauses
The most useful comparison is not between headline percentages but between absolute exposures at defined points. A buyer should calculate the likely bill at seven days, 72 hours, 24 hours and six hours before departure, using the full contracted price and the known third-party charges. That exercise often reveals that a clause which looks generous at the deposit stage becomes expensive close to departure, or that a lower percentage is applied to a broader base.
The exit clause is, in effect, part of the contract's price. It should be negotiated while the commercial relationship is still prospective, not after a diary has moved and the aircraft is waiting. For UK buyers in 2026, the discipline is straightforward: read the ladder, ask what has been committed, and insist that the final bill reflects evidence rather than assumption.